WORLD VISION COMMUNITY BLOG
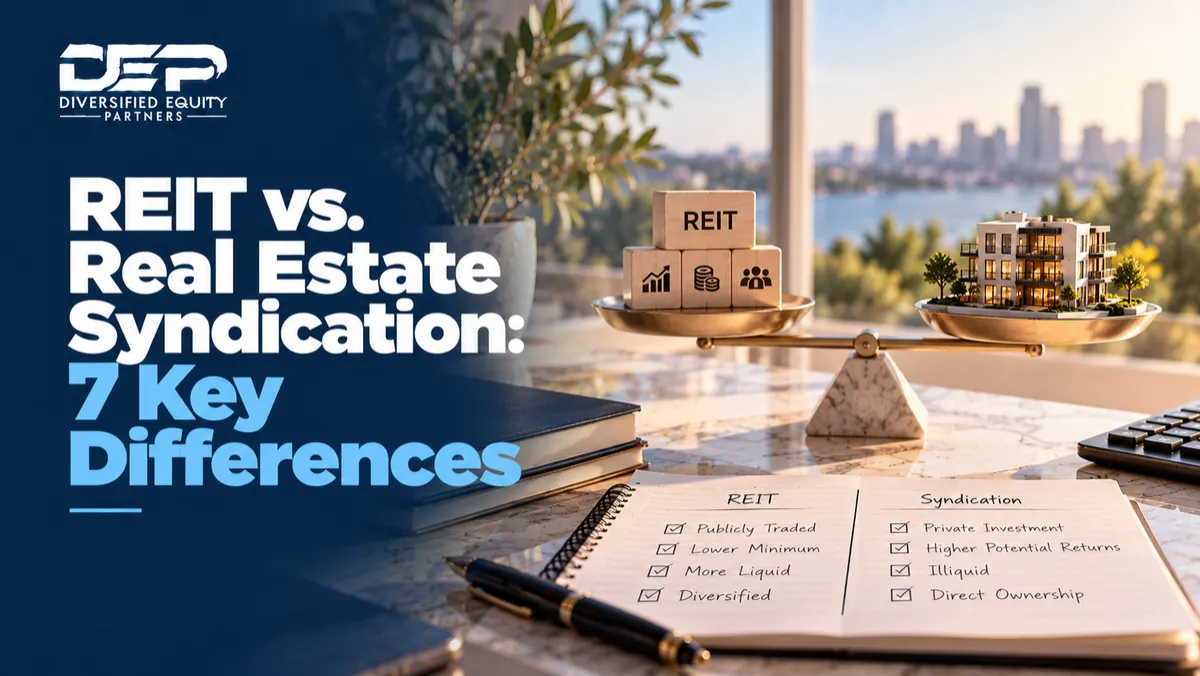
REIT vs. Real Estate Syndication: 7 Key Differences
You like the idea of investing in real estate but becoming a landlord?
Maybe not.
Getting a call about a leaking toilet, dealing with tenants, coordinating contractors, and managing a property can quickly turn an “investment” into another job.
That is why many investors begin exploring more passive ways to invest in real estate.
Two common options are Real Estate Investment Trusts (REITs) and real estate syndications.
Both provide exposure to real estate without requiring you to personally manage a property, but they work very differently.
Here are seven important differences to understand.
What Is a REIT?
A Real Estate Investment Trust, or REIT, is a company that owns, operates, or finances income-producing real estate.
REITs may specialize in apartment communities, industrial properties, data centers, healthcare facilities, shopping centers, self-storage facilities, hotels, or other sectors.
Many REITs trade on major stock exchanges, which makes them relatively easy for everyday investors to access.
When you purchase shares of a publicly traded REIT, however, you are purchasing shares of the company—not directly buying a specific apartment building.
A real estate syndication works differently.
Difference #1: What You Are Investing In
A REIT may own dozens, hundreds, or even thousands of properties across multiple markets.
That can provide significant diversification within one investment.
A real estate syndication is often centered around one specific property or portfolio of properties.
For example, you might invest in a 150-unit apartment community in Dallas.
Before investing, you can review information about that particular property, including:
Location
Purchase price
Current occupancy
Rental income
Financing
Renovation plan
Market assumptions
Projected hold period
Sponsor's business plan
REIT: Exposure to a larger portfolio.
Syndication: Greater visibility into the specific asset or portfolio being acquired.
Difference #2: Ownership Structure
When you purchase shares of a REIT, you own shares in the company that owns or finances the real estate.
With many real estate syndications, investors purchase an interest in an entity—often an LLC or limited partnership—that owns the underlying property.
That distinction matters.
A syndication can provide investors with more direct economic exposure to the performance of a particular property, while a REIT investor's return is tied to the performance and market valuation of the REIT.
Difference #3: Access to the Investment
Publicly traded REITs are extremely accessible.
If you have a brokerage account, you can generally purchase REIT shares just as you would purchase other publicly traded stocks.
Private real estate syndications have different requirements.
Many syndications are offered through exemptions under Regulation D.
For example, Rule 506(b) offerings cannot use general solicitation or advertising and may include accredited investors and, subject to specific requirements, a limited number of sophisticated non-accredited investors.
Rule 506(c) offerings can generally be publicly advertised, but purchasers must be accredited investors and their accredited status must be reasonably verified.
Because syndications are private offerings, investors typically need to review offering documents, complete subscription paperwork, and fund their investment before participating.
Difference #4: Minimum Investment
One major advantage of publicly traded REITs is their low barrier to entry.
Because you are purchasing shares, you can potentially begin investing with a relatively small amount of capital.
Private real estate syndications typically require significantly more.
Minimum investments vary by offering and sponsor and might be:
$25,000
$50,000
$100,000+
There is no universal minimum.
Investors should always review the specific offering documents before making an investment decision.
Difference #5: Liquidity
This may be one of the biggest differences.
Shares of publicly traded REITs can generally be bought and sold during normal market hours.
That provides investors with liquidity if they decide they want access to their capital.
Private real estate syndications are typically much less liquid.
A syndication may have a projected hold period of three, five, seven, or more years.
During that period, there may be limited or no ability to sell your investment.
That means investors should generally view money invested in a private syndication as long-term capital.
Neither structure is automatically better.
Liquidity can be valuable, but long-term private ownership may appeal to investors who do not need immediate access to their investment capital.
Difference #6: Tax Treatment
Real estate can provide unique tax considerations, but REITs and syndications are treated differently.
Private real estate investments structured as partnerships may pass certain income, gains, losses, and deductions through to investors using a Schedule K-1.
Depreciation and other deductions associated with the underlying property may affect an investor's taxable income from the investment.
However, this does not mean every passive investor can automatically use real estate losses to offset salary or other active income.
Passive activity, basis, at-risk, and other tax rules can limit how losses may be used.
REIT investors generally receive dividend reporting rather than the same direct partnership-level tax treatment.
The exact tax impact of either investment depends heavily on the individual investor's circumstances.
Always discuss the tax consequences of an investment with a qualified tax professional.
Difference #7: Return Profile
This is where investors need to be especially careful when comparing REITs and syndications.
There is no guaranteed return for either investment.
Publicly traded REIT returns are influenced by:
Property performance
Dividends
Interest rates
Economic conditions
Investor sentiment
Changes in the REIT's stock price
Because REITs trade publicly, their value can move daily even when the underlying properties have not materially changed.
Real estate syndication returns are generally tied more directly to the property's business plan.
Potential returns may come from:
Property cash flow
Rental growth
Increased net operating income
Principal reduction
Appreciation
Refinancing
Proceeds when the property is eventually sold
Sponsors may provide projected returns such as preferred return, internal rate of return, average annual return, or equity multiple.
Those numbers are projections not promises.
Actual results depend on the property's performance, financing, market conditions, expenses, execution, and eventual exit.
REIT vs. Syndication: Which One Is Better?
Neither investment is automatically better.
They solve different problems.
A publicly traded REIT may make sense for someone who wants:
A lower investment minimum
Easy access through a brokerage account
Greater liquidity
Broad diversification
Real estate exposure without selecting individual properties
A real estate syndication may appeal to someone who wants:
Exposure to a specific property or portfolio
Greater visibility into the investment's business plan
A long-term private real estate investment
Professional management without becoming a landlord
Potential partnership-level tax treatment
You also do not necessarily have to choose one or the other.
Some investors use REITs as part of their liquid investment portfolio while also allocating capital to private real estate.
The Bigger Question
Instead of asking:
“Are REITs or syndications better?”
A better question may be:
“Which investment structure better fits my goals?”
Consider your available capital, liquidity needs, investment timeline, risk tolerance, tax situation, and how much visibility you want into the underlying real estate.
For busy professionals and business owners who want to participate in larger real estate investments without taking on the responsibilities of becoming a landlord, passive multifamily syndications are one option worth understanding.
At Diversified Equity Partners, our goal is to educate investors about how passive multifamily investing works so they can evaluate opportunities and determine whether they align with their individual goals.
Want to learn more about passive multifamily investing? Join the DEP Investor List by clicking this link to receive educational resources and learn about future opportunities.
Private real estate investments involve risk, including the potential loss of principal and limited liquidity. Projected returns are not guaranteed. This article is for educational purposes only and should not be considered financial, legal, or tax advice.
FAQS
WORLD VISION COMMUNITY BLOG
REIT vs. Real Estate Syndication: 7 Key Differences
You like the idea of investing in real estate but becoming a landlord?
Maybe not.
Getting a call about a leaking toilet, dealing with tenants, coordinating contractors, and managing a property can quickly turn an “investment” into another job.
That is why many investors begin exploring more passive ways to invest in real estate.
Two common options are Real Estate Investment Trusts (REITs) and real estate syndications.
Both provide exposure to real estate without requiring you to personally manage a property, but they work very differently.
Here are seven important differences to understand.
What Is a REIT?
A Real Estate Investment Trust, or REIT, is a company that owns, operates, or finances income-producing real estate.
REITs may specialize in apartment communities, industrial properties, data centers, healthcare facilities, shopping centers, self-storage facilities, hotels, or other sectors.
Many REITs trade on major stock exchanges, which makes them relatively easy for everyday investors to access.
When you purchase shares of a publicly traded REIT, however, you are purchasing shares of the company—not directly buying a specific apartment building.
A real estate syndication works differently.
Difference #1: What You Are Investing In
A REIT may own dozens, hundreds, or even thousands of properties across multiple markets.
That can provide significant diversification within one investment.
A real estate syndication is often centered around one specific property or portfolio of properties.
For example, you might invest in a 150-unit apartment community in Dallas.
Before investing, you can review information about that particular property, including:
Location
Purchase price
Current occupancy
Rental income
Financing
Renovation plan
Market assumptions
Projected hold period
Sponsor's business plan
REIT: Exposure to a larger portfolio.
Syndication: Greater visibility into the specific asset or portfolio being acquired.
Difference #2: Ownership Structure
When you purchase shares of a REIT, you own shares in the company that owns or finances the real estate.
With many real estate syndications, investors purchase an interest in an entity—often an LLC or limited partnership—that owns the underlying property.
That distinction matters.
A syndication can provide investors with more direct economic exposure to the performance of a particular property, while a REIT investor's return is tied to the performance and market valuation of the REIT.
Difference #3: Access to the Investment
Publicly traded REITs are extremely accessible.
If you have a brokerage account, you can generally purchase REIT shares just as you would purchase other publicly traded stocks.
Private real estate syndications have different requirements.
Many syndications are offered through exemptions under Regulation D.
For example, Rule 506(b) offerings cannot use general solicitation or advertising and may include accredited investors and, subject to specific requirements, a limited number of sophisticated non-accredited investors.
Rule 506(c) offerings can generally be publicly advertised, but purchasers must be accredited investors and their accredited status must be reasonably verified.
Because syndications are private offerings, investors typically need to review offering documents, complete subscription paperwork, and fund their investment before participating.
Difference #4: Minimum Investment
One major advantage of publicly traded REITs is their low barrier to entry.
Because you are purchasing shares, you can potentially begin investing with a relatively small amount of capital.
Private real estate syndications typically require significantly more.
Minimum investments vary by offering and sponsor and might be:
$25,000
$50,000
$100,000+
There is no universal minimum.
Investors should always review the specific offering documents before making an investment decision.
Difference #5: Liquidity
This may be one of the biggest differences.
Shares of publicly traded REITs can generally be bought and sold during normal market hours.
That provides investors with liquidity if they decide they want access to their capital.
Private real estate syndications are typically much less liquid.
A syndication may have a projected hold period of three, five, seven, or more years.
During that period, there may be limited or no ability to sell your investment.
That means investors should generally view money invested in a private syndication as long-term capital.
Neither structure is automatically better.
Liquidity can be valuable, but long-term private ownership may appeal to investors who do not need immediate access to their investment capital.
Difference #6: Tax Treatment
Real estate can provide unique tax considerations, but REITs and syndications are treated differently.
Private real estate investments structured as partnerships may pass certain income, gains, losses, and deductions through to investors using a Schedule K-1.
Depreciation and other deductions associated with the underlying property may affect an investor's taxable income from the investment.
However, this does not mean every passive investor can automatically use real estate losses to offset salary or other active income.
Passive activity, basis, at-risk, and other tax rules can limit how losses may be used.
REIT investors generally receive dividend reporting rather than the same direct partnership-level tax treatment.
The exact tax impact of either investment depends heavily on the individual investor's circumstances.
Always discuss the tax consequences of an investment with a qualified tax professional.
Difference #7: Return Profile
This is where investors need to be especially careful when comparing REITs and syndications.
There is no guaranteed return for either investment.
Publicly traded REIT returns are influenced by:
Property performance
Dividends
Interest rates
Economic conditions
Investor sentiment
Changes in the REIT's stock price
Because REITs trade publicly, their value can move daily even when the underlying properties have not materially changed.
Real estate syndication returns are generally tied more directly to the property's business plan.
Potential returns may come from:
Property cash flow
Rental growth
Increased net operating income
Principal reduction
Appreciation
Refinancing
Proceeds when the property is eventually sold
Sponsors may provide projected returns such as preferred return, internal rate of return, average annual return, or equity multiple.
Those numbers are projections not promises.
Actual results depend on the property's performance, financing, market conditions, expenses, execution, and eventual exit.
REIT vs. Syndication: Which One Is Better?
Neither investment is automatically better.
They solve different problems.
A publicly traded REIT may make sense for someone who wants:
A lower investment minimum
Easy access through a brokerage account
Greater liquidity
Broad diversification
Real estate exposure without selecting individual properties
A real estate syndication may appeal to someone who wants:
Exposure to a specific property or portfolio
Greater visibility into the investment's business plan
A long-term private real estate investment
Professional management without becoming a landlord
Potential partnership-level tax treatment
You also do not necessarily have to choose one or the other.
Some investors use REITs as part of their liquid investment portfolio while also allocating capital to private real estate.
The Bigger Question
Instead of asking:
“Are REITs or syndications better?”
A better question may be:
“Which investment structure better fits my goals?”
Consider your available capital, liquidity needs, investment timeline, risk tolerance, tax situation, and how much visibility you want into the underlying real estate.
For busy professionals and business owners who want to participate in larger real estate investments without taking on the responsibilities of becoming a landlord, passive multifamily syndications are one option worth understanding.
At Diversified Equity Partners, our goal is to educate investors about how passive multifamily investing works so they can evaluate opportunities and determine whether they align with their individual goals.
Want to learn more about passive multifamily investing? Join the DEP Investor List by clicking this link to receive educational resources and learn about future opportunities.
Private real estate investments involve risk, including the potential loss of principal and limited liquidity. Projected returns are not guaranteed. This article is for educational purposes only and should not be considered financial, legal, or tax advice.
LEARN WHAT PASSIVE REAL ESTATE INVESTING CAN DO FOR YOU AND YOUR FAMILY!
LEARN WHAT PASSIVE REAL ESTATE INVESTING CAN DO FOR YOU AND YOUR FAMILY!
WV Capital Holdings does not make investment recommendations, and no communication through this website or in any other medium should be construed as such. Investment opportunities posted on this website are "private placements" of securities that are not publicly traded, are subject to holding period requirements, and are intended for investors who do not need a liquid investment. Private placement investments are NOT bank deposits (and thus NOT insured by the FDIC or by any other federal governmental agency), are NOT guaranteed by WV Capital Holdings and may lose value. Neither the Securities and Exchange Commission nor any federal or state securities commission or regulatory authority has recommended or approved any investment or the accuracy or completeness of any of the information or materials provided by or through the website. Investors must be able to afford the loss of their entire investment. Any financial projections or returns shown on the website are estimated predictions of performance only, are hypothetical, are not based on actual investment results and are not guarantees of future results. Estimated projections do not represent or guarantee the actual results of any transaction, and no representation is made that any transaction will, or is likely to, achieve results or profits similar to those shown. Any investment information contained herein has been secured from sources that WV Capital Holdings believes are reliable, but we make no representations or warranties as to the accuracy of such information and accept no liability therefor. Offers to sell, or the solicitations of offers to buy, any security can only be made through official offering documents that contain important information about risks, fees and expenses. Investors should conduct their own due diligence, not rely on the financial assumptions or estimates displayed on this website, and are encouraged to consult with a financial advisor, attorney, accountant, and any other professional that can help you to understand and assess the risks associated with any investment opportunity. Investments in private placements involve a high degree of risk and may result in a partial or total loss of your investment. Private placements are generally illiquid investments. Investors should consult with their investment, legal, and tax advisors regarding any private placement investment.
QUICK LINKS
WV Capital Holdings specializes in value-add multifamily real estate and exhibits an expertise in maximizing value on every asset we acquire. Rather than attempting to predict the market cycles, we strive to acquire cash flowing apartment communities within medium and larger US metro.
© 2024 WV Capital Holdings. All Rights Reserved.